The honest answer to whether home insurance covers water damage is that it depends on where the water came from. Sudden and accidental damage, such as a burst pipe or a failed appliance hose, is often covered by a standard homeowners policy. Damage from a slow leak, poor maintenance or rising flood water is often not.
Your policy is the final word, and your insurer decides each claim. This guide explains the usual pattern so you know what to ask, and what to do in the first day to protect a claim you may want to make.
The Usual PatternSudden Damage Versus Slow Damage
These are general patterns, not promises. Policies differ, so read yours or ask your agent.
| What happened | Often covered? | Why it matters |
|---|---|---|
| Burst supply line or frozen pipe | Often yes | Sudden and accidental, which is the core of most policies |
| Washing machine hose failure | Often yes | Sudden failure of a household system |
| Slow leak behind a wall over months | Often no | Gradual damage and maintenance exclusions are common |
| Roof leak after a storm | Often yes for the storm damage | Depends on cause, age of roof and deductible |
| Sewer or drain backup | Only with an endorsement | Many policies need added coverage for backups |
| Rising flood water from outside | Usually no | Flood normally needs a separate flood policy |
Why Flood Is Treated Differently
Standard homeowners policies commonly exclude damage from rising surface water, and flood insurance is a separate product. If a storm sends water into your basement through the ground or a window well, the policy question can turn on exactly how the water entered. That is one reason the first photos matter.
Check your declarations page for flood and sewer backup coverage before you need it. If you are unsure, ask your agent which events your policy lists and which it excludes.
First DayWhat To Do In The First Day
Acting quickly protects your home and your claim. A reasonable order looks like this.
- Stop the water if it is safe, starting with the main valve for a supply line.
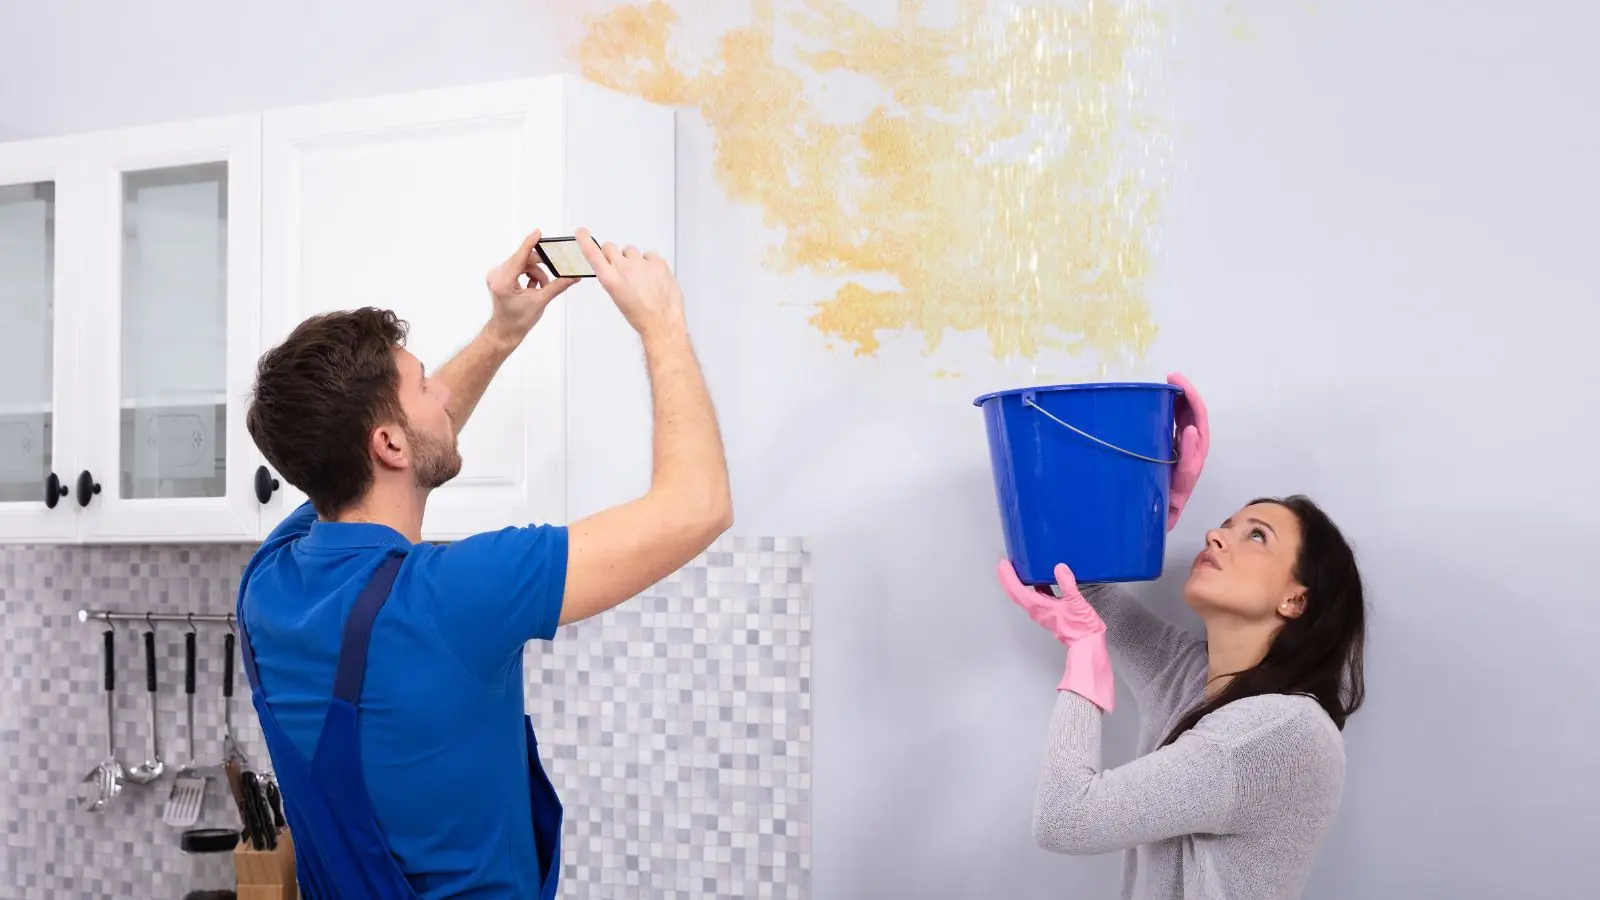
- Photograph and video everything before it is moved or thrown away, including the source of the leak.
- Contact your insurer or agent and ask what they need and whether to start drying right away.
- Move valuables out of the wet area and write down what was damaged.
- Call a restoration crew to extract water and start drying, and keep the written scope and moisture readings.
- Keep every receipt, including hotel stays if the house is not livable.
What The Colorado Division Of Insurance Says
The Colorado Division of Insurance publishes a consumer advisory on burst pipe claims. It says burst pipes and the resulting water damage are generally covered by homeowners and renters policies, and it advises policyholders to contact their insurer as soon as possible after the damage.
The same advisory says to get the company's instructions before making repairs, to include an inventory of damaged property with the claim and to keep receipts and other records.
It notes that providing information in bits and pieces slows a claim down, and that additional living expenses may be claimed when a covered loss makes the home unlivable. For Commerce City homeowners the practical point is simple. Photograph first, call your insurer early and send the full set of documents together.
Want The Damage Documented?
Call the 24/7 line for photos, moisture readings and a written scope.
What A Restoration Crew Can Provide For A Claim
A restoration crew does the physical work, and it also creates records. Moisture readings show how far the water spread. Photos show the starting condition. A written scope lists what will be removed, dried and rebuilt. These documents give your insurer a clear picture and give you a record of what you were told.
A crew cannot promise that your claim will be approved, and it cannot set your deductible or tell you what your policy pays. Those answers come from your insurer. What the crew can do is stop the damage from growing while the claim is processed, which is often what the policy expects you to do.
If the water is still active, begin with emergency water removal and then water mitigation so the building dries before mold starts.
MoneyDeductibles And Out-Of-Pocket Costs
Your deductible is the amount you pay before coverage begins. For small losses the repair cost may be close to or below the deductible, so a claim may not pay anything. Some policies also use separate deductibles for certain causes of loss. Ask your agent which deductible applies to water damage.
Even when a claim is not filed, the same records help. They let you compare scopes, they support a later claim if hidden damage appears, and they help when you sell the house.
Nearby TownsSame Rules Across The Denver Area
Insurance rules do not change at the city line, so the steps above apply the same way in Denver, Brighton and the rest of the area. What does change is the water or sewer provider. Ask your utility if the water came from a public line.
FAQCommon Questions
Does homeowners insurance cover a burst pipe?
Often yes. The Colorado Division of Insurance says burst pipes and the resulting water damage are generally covered by homeowners and renters policies. Your own policy decides the details, so ask your insurer.
Should I call my insurer before or after I call a restoration crew?
Call both quickly. The Colorado Division of Insurance advises contacting your insurer as soon as possible, and it says to get their instructions before making repairs. Stopping and drying the water is usually expected while the claim is open.
Is a slow leak covered?
Often not. Gradual damage and maintenance problems are commonly excluded. If you are unsure whether a leak was sudden, document the date and the symptoms and ask your insurer.
Does home insurance cover flood damage from a storm?
Standard policies commonly exclude flood from rising water, and separate flood insurance covers it. Check your policy.
What if my claim is delayed or denied in Colorado?
Ask your insurer for the reason in writing. The Colorado Division of Insurance Consumer Services Team handles claim questions and complaints at 303-894-7490 or 800-930-3745.
Can a restoration company tell me whether I am covered?
No. Coverage decisions belong to your insurer. A restoration crew can provide photos, moisture readings and a written scope to support your claim.
Water still spreading? Call (303) 952-8295 and a crew can be dispatched the same day when available.